
Two Questions Answered, Two to Go
Nov 06, 2026Another question answered, but the third question just got cloudier.
TL;DR
- Democratic victories in key data center markets have increased the likelihood of a more contested, expensive and potentially slower AI buildout.
- Markets have a habit of throwing the baby out with the bathwater, especially when indiscriminate selling is driven by headlines or one-off events. This is sell first, find the answers later.
- The ultimate question becomes one of timing. There is a mismatch between AI spending and the revenue it generates.
- We may be nearing capitulation-type readings on key indicators like the semiconductor index, but the tape hasn't confirmed the bottom.
In September I wrote that four known unknowns were hanging over markets: what the Fed would do about inflation, who would control Congress, where oil goes with Iran, and whether the AI spending boom will ever pay for itself. The Fed question closed on September 16. The election question closed Tuesday night.
This memo covers what the voters decided, why stocks fell anyway, and where that leaves the scorecard.
What the voters decided
The midterms are now complete and the result was unequivocal. In the client commentary we recorded in September, I said the largest risk to this market was political. I clarified that it didn't matter who won the midterms. What mattered was what came out of it in terms of anti-AI regulation.
Democrats won both chambers handily. In the Senate they flipped at least seven seats, including Texas, and will hold at least 54 seats in January. In the House they will start the year with their largest majority in nearly two decades. Michael Townsend at Schwab summed it up: “The scope of the Democratic victory exceeded even the wildest of predictions.”
For the next two years that means divided government. The President keeps the veto, executive orders and tariff authority. Congress controls spending, committees and confirmations, including any new Fed governors. Large new tax or spending bills are unlikely in either direction, which markets have historically treated as a feature, not a bug.
Why stocks fell on Thursday, November 5
The selling started before election day, which some will take to mean it had nothing to do with the election. I read it the other way: the market sniffed out the winner ahead of time and sold the stocks the winner's platform threatens. In September I noted that the market's midterm move historically begins about a month before the vote, as the polls firm. This year it did, but in the wrong direction for most stocks.
The clues are in what sold off. The semiconductor index fell 12% in the three sessions before election day, and the Nasdaq 100 was in correction by Monday, November 2, a day before the polls opened. The semiconductor index is down 31.3% over the trailing month.
This makes intuitive sense if you believe, as the market seems to, that Democrats would restrain the data center buildout. A narrow Democratic House would have meant gridlock and little else. A sweep of this size points to a mandate, and the anti-data-center movement is the part the market cares about. To be fair, the anti-data-center narrative was largely bipartisan in many localities.
The Texas gubernatorial race became a flashpoint for the issue in the final weeks before the election. Texas is the center of the data center buildout and will host 25% of all data centers coming online between now and 2030.
Nationwide, 29 of 30 ballot measures restricting the data center buildout passed on Tuesday. These measures are non-binding. But given the size of the Democrats' victory, the Texas governorship, and a 29-to-1 tally in favor of restrictions, politicians who want to remain employed as politicians are going to heed the message.
Restricting the buildout will hit the semiconductors first. They are the picks and shovels, and nothing in a data center runs without them. This is why the semiconductor index has fallen this hard. This is also the opportunity.
The market is shifting toward pricing an environment where no more data centers get built, much like nuclear power plants after Three Mile Island. But the new Texas leadership only wants to slow the buildout, not end it. I also think it will be nearly impossible to end it. And the proposed restrictions mostly apply to projects that have not broken ground, not to data centers already under construction.
So the election answered its question, and the answer came with a steep market decline. In September the AI question was: will the spending pay off? The evidence still says yes. Amazon and Alphabet said last week that demand is ahead of the capacity they can install. The question now has a second part: will the spending be allowed?
SEPTEMBER: Will the AI spending pay off?
TODAY: Will it pay off, and will it be allowed to be built?
My take: slow, not stop, but the margin of victory raises the odds of more moratoriums. The case for calm: governors control permits, grid connections and tax incentives, not federal law, and any federal restriction would need the President's signature. Texas' new governor faces a Republican legislature. Governor Abbott, a Republican, had already frozen new grid connections in August. And a project blocked in Texas can always be built in another state. Dan Ives, a longtime AI bull, said tech “needs to adjust and focus on a slower pace of this AI rollout.”
This may be a good thing. One of the variables causing investors' agita was the amount the hyperscalers (the largest cloud companies) are spending on new data center construction. The constraints may be a positive for investors who think these massive companies are spending too much.
The case for concern: a mandate this large invites copycats. Other governors will read the Texas result, and a Democratic Congress can hold hearings and attach conditions to federal permitting. When one category of spending accounts for a third to a half of economic growth, a political brake on that category is a macro event.
No one knows how hard the brake gets pressed, which is why the AI question stays open with a wider range of potential outcomes than it had two months ago. Remember what I said a few months ago: uncertainty is immediately sold. Investors sell first and ask questions later. Investors have no idea how far the new Congress will go, so they are selling indiscriminately.
This is what occurred today. The worst-case scenario is being priced into the markets. And in some cases, the worst-case scenario is not even rational.
This is a classic washout event, with $2.8 trillion wiped out of the markets in a single day. That is the largest single-day dollar loss in US stock market history. 1
The demand for compute and semiconductors of all types remains massive, and it is sold out for at least another year. Nvidia trades at less than 12x forward earnings. That compares to 17.8x for the S&P 500, a six-point discount. At the same time, Nvidia's earnings are expected to grow 95% and 71% over the next two years, compared to 32.0% and 16.3% for the S&P 500 as a whole. 2
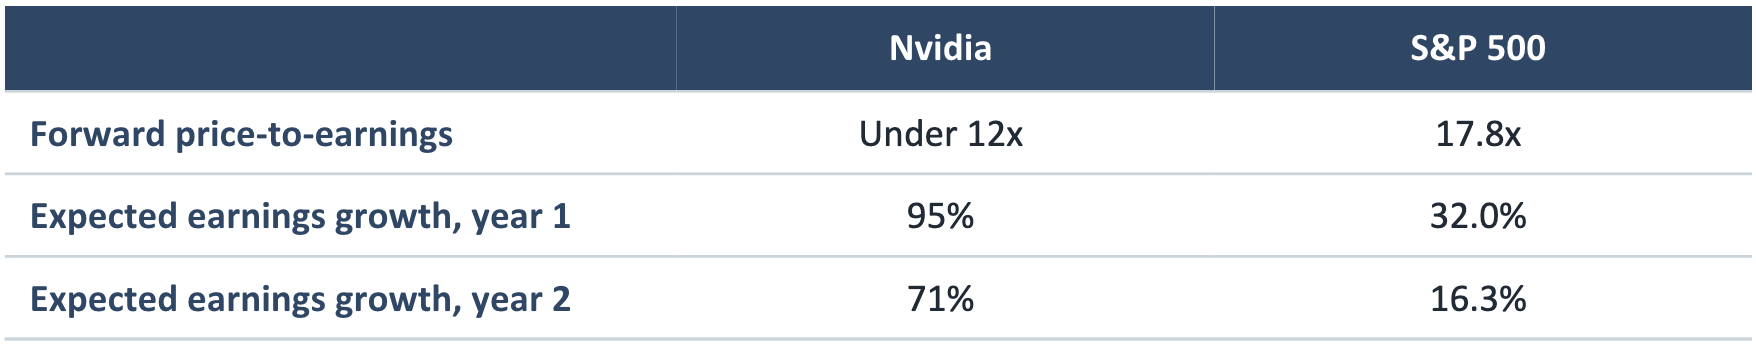
Source: Bianco Research. Forward estimates are consensus expectations and may not be realized.
So you get a company growing at nearly three times the speed, trading at a much lower valuation. The market is embedding far too much pessimism into the AI trade.
What we are doing about it
Nothing changes at this point. We've built durable portfolios from assets with low correlations to each other. One of the positive things that occurred recently was a re-establishment of the classic correlation: stocks down, bonds up. That is what has happened in the last few weeks. Rates topped out and moved sharply lower.
We noted the rise in rates was likely overdone and that rates would likely move down. We've also seen closed-end bond fund discounts tighten a bit, giving our bond sleeves a tailwind. Of course, that didn't offset the equity losses, but it did reduce them.
We will be patient and opportunistic, taking advantage of the selloff. I still believe the market is offside here and that data center construction will likely slow only slightly, and that is more than baked in today.
Thankfully, we've moved aggressively into structured notes and buffer ETFs that use built-in protection to reduce downside volatility. That will also help mitigate losses on equity sleeves.
If you have any questions or concerns, please do not hesitate to reach out to us.
Sincerely,
Mark J. Asaro, CFA
Partner, CIO, Noble Wealth Management
Sources: Bianco Research (ballot measure count, single-day market loss, Texas share of planned data centers, valuation and earnings growth figures); Schwab; company re11ports. Market data are as of November 5, 2026 and change daily. Educational purposes only; not individualized investment, tax or legal advice. Index figures are unmanaged and cannot be invested in directly. Forward-looking statements reflect the author's opinion and may not come to pass. Structured notes and buffer ETFs carry their own risks, including issuer credit risk and capped upside. All investing involves risk, including loss of principal.
1. https://www.marketwatch.com/story/tech-stocks-log-worst-day-since-2020-as-carnage-comes-to-the-ai-trade-56109845
2. yCharts data connected through Claude
Author


